
Intergenerational wealth transfer is a sensitive subject for families, particularly wealthy ones. Yet they generally make the same mistake: they start with the money, turning first to investments, taxes, legal structures and wills. A question is asked far less often: before any money is lost, what else has already been lost?
Behind every great fortune lie years of decisions, risk, and experience. The problem is that what enabled one generation to build wealth does not automatically pass to the next. A family may have designed intricate legal structures for its assets yet have no plan for preparing the people who will one day steer those assets.
Perhaps this is exactly where the paths of two families diverge. Some fortunes erode by the second or third generation, while others remain standing even after major upheavals. The real question is not “What will reach the next generation?” It is “Has the next generation been prepared to preserve family wealth and to steer what it receives?” In this Genar article, we address that question.
When Three Lives Rest on One Asset
A family that owns a family business or substantial wealth does not face a simple system. In 1978 at Harvard Business School, Renato Tagiuri and his doctoral student John Davis began developing a framework that would later become one of the best-known models in the field of family business: the Three-Circle Model of the family business.
The framework separates three domains: family, ownership, and business. The idea first took shape in the work of two researchers in the 1970s, appeared in Davis’s doctoral dissertation in 1982, and eventually became one of the most-cited papers in the field through an article titled “Bivalent Attributes of the Family Firm” in 1996.
The model’s core idea is simple and practical: not all family disputes are disputes between people; many are disputes between roles. A father who is the principal owner of the company says the final decision is his, while his son, the CEO, believes the authority to manage should rest with him. Both may be entirely reasonable from their perspective. The problem is not their personalities; it is a mistaken understanding of ownership and management, two concepts that must not be confused.
As the family grows, this complexity grows with it. The number of owners increases, some enter the business, and some stay outside; under these conditions, a simple family relationship must answer emotional, ownership, and management concerns at the same time.
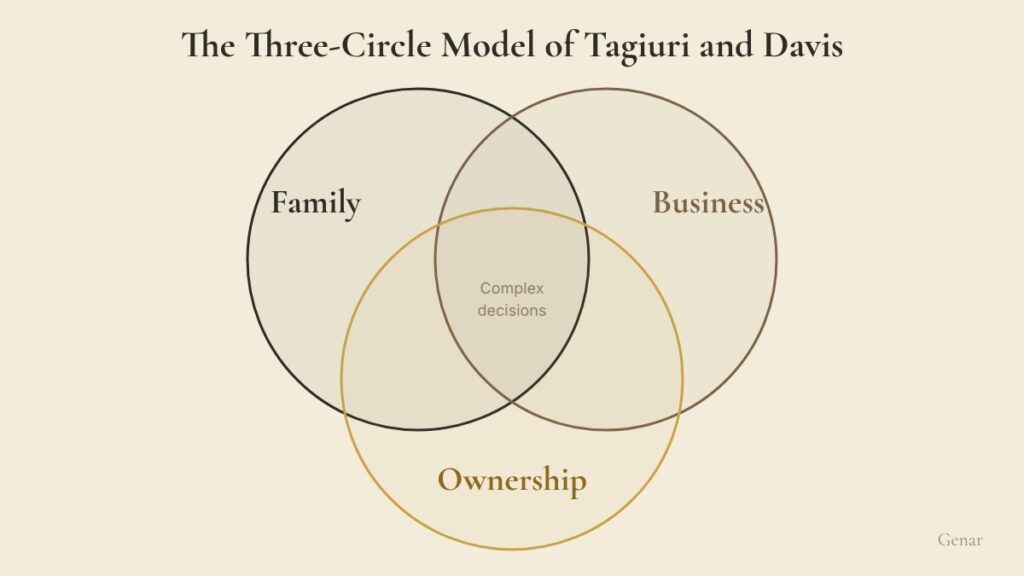
This is exactly where structure becomes important. One person can be a family member, an owner and a manager at the same time. Another can be only a family member and owner with no role in management. A professional CEO can run the company with no family relationship at all. A sentence such as “This decision is in the family’s interest” is therefore not enough on its own. One must ask: in the interest of the family in which role, and in the interest of which generation?
The Family Needs Governance Too
When governance comes up, the mind usually goes to the board of directors and the bylaws. But a family that owns a business faces another question: how does the family itself make decisions?
In the family business literature, this is called family governance. It means creating mechanisms for dialogue, decision-making, role definition and dispute management among the family, ownership and the business. The family council, the family assembly and the family charter are among the tools that more complex families use for this purpose.
But the philosophy behind these structures matters more than their impressive titles: important issues should not be resolved for the first time in the middle of a crisis. What effect would it have on the business if one family member wanted to sell their shares? What disputes would arise if one person wanted to join the business and the others believed they lacked the necessary qualifications? These are not questions that can be answered with rules written in a moment of crisis. Good governance is not meant to eliminate disagreement; it is meant to keep disagreement from dragging the entire system down.
But Structure Does Not Build People
Now suppose the family has taken all these steps: it has set the rules, formed a board, refined the ownership structure and drafted the contracts with precision. All of this is necessary, but one question remains: are the people who will make decisions within this structure prepared for it?
A structure can specify who has the right to vote, but it cannot give anyone the power of judgment. A contract can determine who owns what, but it cannot teach an heir when to hold an asset and when to change it. This is where the issue of succession shows itself.
Being an Heir Is a Status; Becoming a Successor Is a Process
Someone may become the heir to a large business merely by being born into a family. But no one becomes a leader by birth alone; leadership has to be built. The next generation needs the chance to make decisions, accept responsibility, face the results of its own choices, make mistakes and learn from them.
In the family business literature, successor development is not merely the transfer of a title or shares; it is the simultaneous preparation of the family and the business to continue on their path in the next generation. An heir receives something, but a successor has acquired the ability to continue that path. The two concepts are not the same, and this is where intergenerational wealth transfer goes beyond a purely legal matter.
Succession planning is usually a gradual path: first learning, then participating in some decisions, accepting real responsibilities, gaining greater authority at the next step and finally, if the person has shown the necessary competence, reaching a position of leadership. Successful succession does not happen on the day of the transfer; it must have been built years before.
Financial Literacy Is Not Enough
Suppose the next generation knows what a company is worth, what a balance sheet is and what return an asset yields. Does this knowledge mean readiness to steer wealth? Not necessarily. In the real world, important decisions do not always have a single right answer or a clear formula. What if the market crashes? What if the best economic decision conflicts with the wishes of part of the family?
This is where financial literacy differs from competence in steering wealth. Financial literacy helps a person understand the numbers; competence helps a person exercise judgment when the answer is not known in advance.
Wealth Is Not Always Visible in Financial Statements
One key concept in family business research is socioemotional wealth: the values a family derives from owning and controlling the business that appear in no financial statement, such as family identity, control, belonging and the continued presence of the family.
Luis Gómez-Mejía and his colleagues examined this concept in a well-known 2007 study of family olive oil mill owners in southern Spain. They showed that, to preserve this kind of wealth, families sometimes make decisions that look purely risky from an economic standpoint. The families chose between joining a cooperative (less business risk but loss of family control) and remaining independent (higher risk but retained control), and a large share preferred independence.
Suppose a family receives a very large offer to sell its company. Financially, selling may be the best option, yet the family refuses. This decision is not necessarily irrational. Perhaps the company is not merely an asset to them; it is part of their identity, their name is on it and their history was formed within it. Before judging a family’s decision, ask what that family considers valuable. Sometimes the answer is not money.
When Values Are Not Defined
The problem begins when a family has never had a real conversation about its values. In such circumstances, in every dispute each person will hold their own definition of the “family’s best interest.” One member believes the company should be preserved because it is the family legacy. Another holds that the father was a risk-taker oriented toward growth and would have changed the company if he were alive today. Both consider themselves loyal to the legacy; only their definitions of legacy differ.
For this reason, family values should not be merely a pretty sentence on the wall; they must show themselves in real decisions. What must never be sacrificed? If a conflict arises between preserving the legacy and building the future, which takes priority? Such conversations may seem unnecessary on calm days, but they are vital precisely for difficult days.
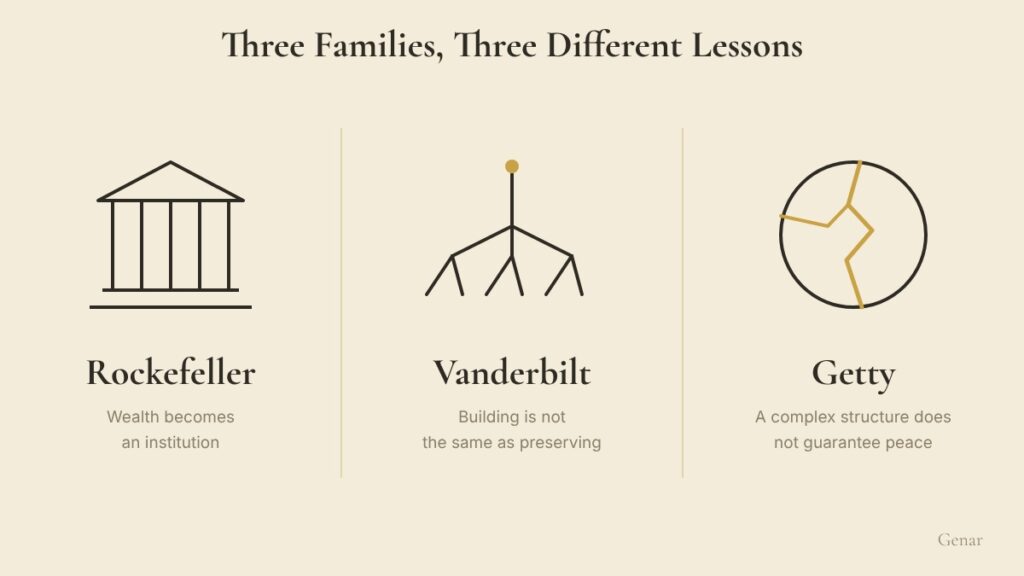
Three Families, Three Different Lessons
The history of wealthy families offers no definitive formula for continuing a family business. However, three stories in particular clarify the question of intergenerational wealth transfer: the Rockefellers, the Vanderbilts and the Gettys. All three built immense fortunes, yet each carries a different lesson about how that fortune endures.
Rockefeller: When Wealth Becomes an Institution
John D. Rockefeller, founder of Standard Oil, built one of the largest fortunes in American history. But his story is not only about how much money remained for later generations. In 1913, the Rockefeller Foundation was established with a mission the foundation says has not changed since its first day: to promote the well-being of humanity throughout the world.
Between 1913 and 1929, the Rockefeller family devoted substantial capital to the foundation, which, by its own figures, has distributed more than $26 billion in philanthropic capital worldwide over more than a century.
The interesting point is that Rockefeller did not think only about “holding on to money.” Part of his wealth entered an institutional structure meant to serve a specific purpose, independent of any one person’s lifespan. The lesson of this story is not to establish a charitable foundation. The deeper lesson is that wealth can shift from a personal asset to an institution with a purpose and a time horizon independent of any one individual. The larger question than “Who owns it?” is “What is meant to remain after the owner?”
Vanderbilt: When Building and Preserving Are Two Different Skills
Cornelius Vanderbilt started in shipping, then moved into railroads and ultimately, by building the New York Central railroad empire, created one of the largest personal fortunes of nineteenth-century America. At his death in 1877, his estate was estimated at about $100 million, a figure that at the time exceeded the U.S. Treasury’s holdings. His son William Henry, who inherited roughly 95 percent of this fortune, not only preserved it but doubled it in less than a decade.
The Vanderbilt story is not one of failure immediately after the founder. It is a story of serious crisis in later generations. After William Henry died, the fortune was split among his children; part of the next generation lost interest in the railroad business, and estate costs and a lavish lifestyle rose. According to historical accounts, when about 120 Vanderbilt descendants gathered in 1973 at the university Cornelius himself had founded, not one of them was a millionaire.
Behind this lay a combination of dispersed ownership, changing economic conditions, an expensive lifestyle and the growing distance of later generations from the process that had created the wealth. The skill of building wealth is not the same as the skill of preserving it. Cornelius had to make decisions under competition and uncertainty; later generations encountered only the outcome of a path, not the difficulty of building it.
Getty: When Great Wealth Builds a More Complex System
- Paul Getty built his immense fortune mainly in the oil industry. But the story of the Getty family is less about “preserving or losing money” than about the growing complexity of ownership, trust structures and family relationships between generations. The Getty family trust, formed in 1934 with about $3.3 million, became, after he died in 1976, the center of one of the most contentious family disputes in wealth history.
According to Fortune magazine’s reporting from that era, Getty’s children and grandchildren entered a long legal battle over control of roughly $4 billion in assets and the way the trust was run. The battle even involved the rights of descendants not yet born, and it finally ended in 1985 when the trust was divided into several smaller parts among the different branches of the family.
As the number of stakeholders grows, the question shifts from “How much money do we have?” to “Who decides, who has control and, if the family disagrees over the interpretation of ownership, who arbitrates?” The Getty story shows that a complex legal structure is not, on its own, a guarantee against disputes. Without governance, dialogue and clear rules, the structure itself can become part of the problem.
From Three Stories to One Pattern
The Rockefeller, Vanderbilt and Getty stories are not identical, but together they make one point clear: in each generation, wealth faces a different problem.
The first generation is usually occupied with creating value: how does one build something that does not yet exist? The next generation must learn to steer well something it did not build itself. In later generations the question grows more complex: how does one build a shared path amid multiple owners and differing interests? For this reason, intergenerational transfer is not an “event”; each generation must prepare for its own particular problem.
Four Layers That Must Be Built Together
To turn this discussion into a practical framework for preparing the next generation to manage wealth, we can see it in four layers.
1. Understanding
The next generation must know how this wealth was built, what decisions drove it, what risks were taken and what mistakes were made. This is the difference between knowing an asset’s value and understanding its story.
2. Competence
Knowing is not enough; the next generation must have the chance to make decisions. The path is usually gradual: learning, participation, responsibility, authority, leadership. The goal is not for the next generation to copy the founder. The goal is for them to create value in their own time, under their own conditions.
3. Governance
When a family grows, the family relationship is no longer enough to resolve every issue. It must be clear who owns, who manages, who makes the final decision and how disputes are resolved.
4. Meaning
Ultimately, the family must know why it wants to continue this wealth. Is the goal only to preserve the value of the assets? Is creating opportunity for the next generation more important than ownership? Does “legacy” mean preserving exactly what the founder built? Or does it mean preserving the ability to create something valuable in every generation?
These questions have no single answer, but a family that has not talked about them will likely be forced, in the hardest moment, to find answers on the spot.
Owner or Steward?
Another useful concept in this discussion is stewardship. Stewardship theory was proposed by James Davis, David Schoorman and Lex Donaldson in 1997 as a counterpoint to the prevailing view of the manager as a purely self-interested individual. They showed that under the right conditions, people can see themselves as serving the long-term interests of the organization and the collective, not only their personal interests.
For wealthy families, this concept raises an intriguing question: are they the owners of these assets or their stewards for the future? These two views produce different decisions. If ownership is only an individual’s “right,” decisions are based on personal interest. But if ownership is joined by stewardship, another question enters: what does this decision mean for those who come later? Stewardship adds a time horizon to the decision without depriving the owner of the freedom to choose.
A Simple Test for Families
Suppose you own a business or a substantial part of the family wealth. Ask yourself these five questions:
Does the next generation know how the family wealth was built?
Has it ever had the chance to make real decisions and experience their results?
Can it distinguish among the roles of “family member,” “owner” and “manager”?
Has our family discussed possible future disputes before they occur?
If the next generation has to change part of what we have built, does it know what must be preserved and what can be changed?
If the answer to some of these questions is “no,” it does not necessarily mean failure. But it is an important sign that part of the transfer architecture has not yet been built.
What Intergenerational Wealth Transfer Must Carry
The question of wealth transfer cannot be solved with a document or a legal structure alone. These tools are necessary, but they are only part of the solution. Alongside assets, other things must also be transferred: knowledge for understanding, competence for making decisions, governance for managing complexity, and meaning for knowing why this path should continue.
At first glance, the question is what intergenerational wealth transfer should transfer. At second glance, the question is what system must be built so that the next generation can make sound decisions with what it receives. These two questions are not alike, and this very difference separates one family’s path from another’s. In Genar’s articles on family and wealth, we have explored this subject from other angles as well.
From Wealth Transfer to an Architecture of Continuity
A family may use the best lawyers, financial advisors, and investment managers, benefit from a precise ownership structure, and have all contracts properly concluded. But if the generation that will make the decisions has not been prepared for that responsibility, part of the problem remains unresolved. On the other hand, educating one generation is not enough on its own either. If roles are unclear and family members have not discussed shared values and the future, even capable people may fail to be productive within a dysfunctional system and may fail to chart a sound path forward.
Continuity of a family business is therefore not the product of a single element; people, structure and meaning must be designed together. This is where wealth transfer shifts from a legal event to an intergenerational project. The question for a family thinking about the future is not only “What are we leaving to our children?” The harder question is this: if everything is placed in their hands tomorrow, will they be prepared for the decisions they must make after us?
A contract can transfer ownership, a structure can regulate power, capital can create opportunity, but competence must be built, governance must be designed and legacy must be given meaning.
Perhaps the most lasting thing one generation can leave the next is not the wealth itself but the ability to build a future in which that wealth can continue to create value. This is the point where Genar’s approach to preparing the next generation begins.